Oklahoma Hailstorms: What Would You Pay to Fix Your Roof?

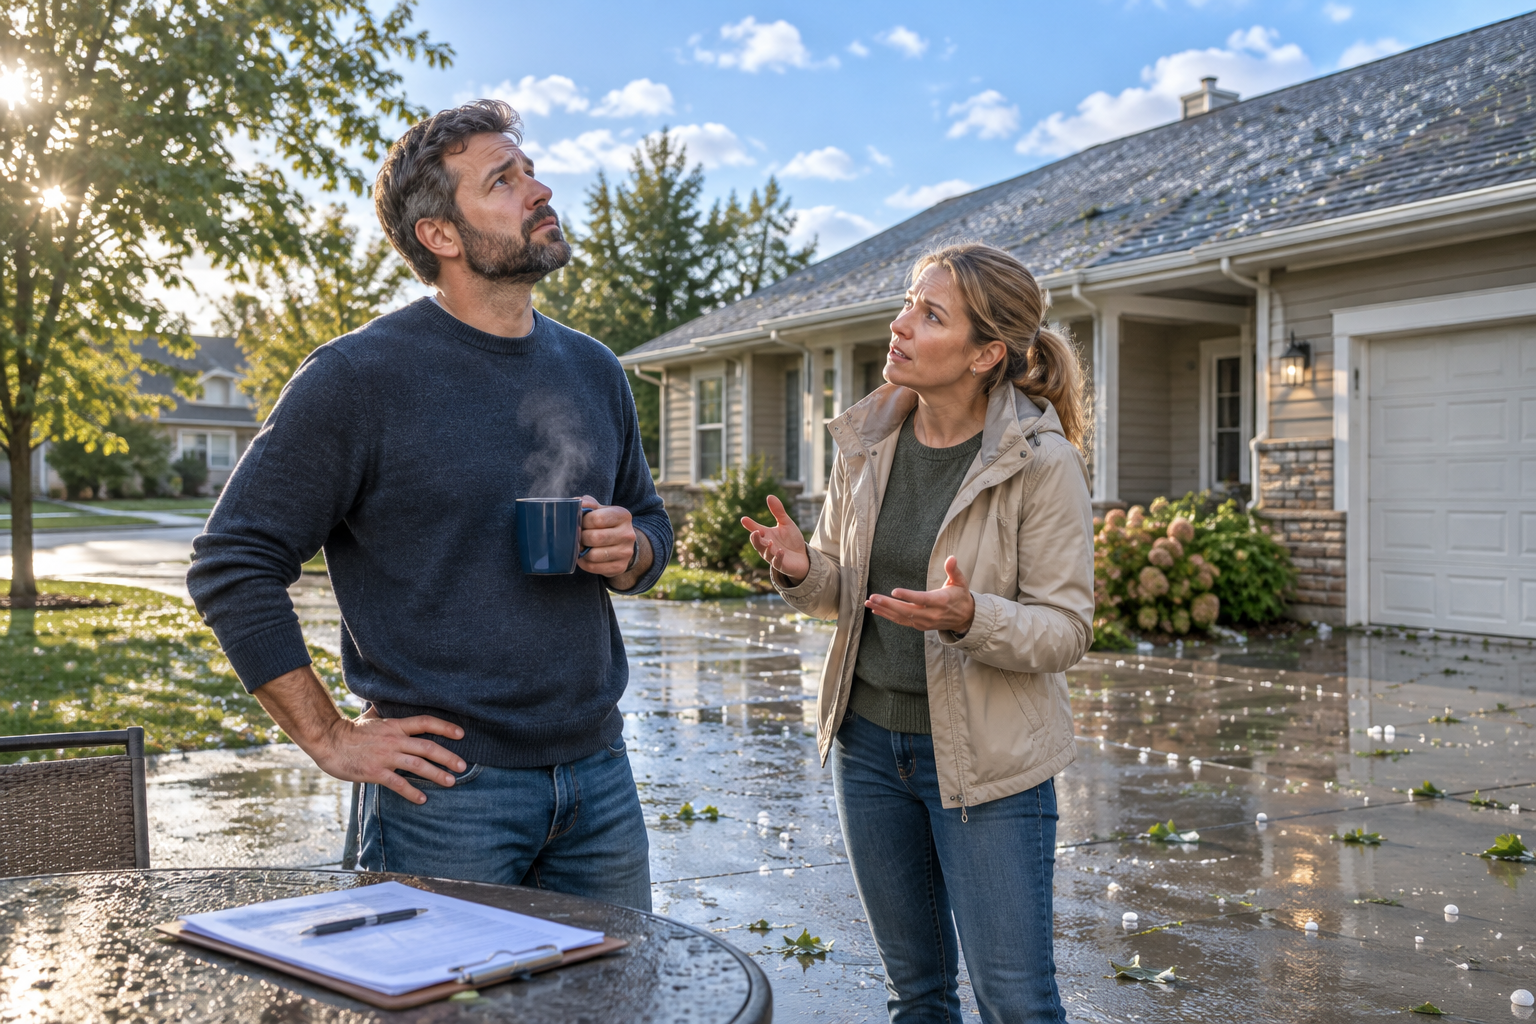
Picture this. An Oklahoma hailstorm rolls through overnight. By breakfast, you’re standing in the driveway, coffee in hand, looking up at the roof. Your neighbor walks over and says his deductible is $1,000. You pull up your own policy and see a percentage. Now you’re doing math before you’ve even had your coffee.
Here’s the question I’d ask before the next storm: If hail damages my roof, how much of the bill comes out of my pocket? You can get that answer on a clear day, with your policy in front of you and your coffee still hot.
Check what you’d pay after a hailstorm
Look for a separate wind or hail deductible. If yours is a percentage, ask your agent to show you what that means in dollars. Then ask how the policy values your roof on a covered claim. Would it pay based on replacement cost, account for the roof’s age and condition, or use a separate payment schedule?
Have a detached garage or shop? Check the coverage limit for that building too. If you use it for work, tell your agent how you use it so they can check the policy with you.
Ask about water damage
A flooded yard, a burst pipe, and a backed-up drain can all leave water in your house. Your policy may treat each one differently. Standard homeowners insurance generally excludes flooding and earthquake damage. Ask how your policy handles sudden leaks, slow leaks, and sewer or drain backups.
Three questions to ask before you renew
- What would my wind or hail deductible be in dollars?
- How would my policy pay for a covered roof claim?
- Which types of water damage would I need separate coverage for?
If you’d like another set of eyes on your policy, have your declarations page and any endorsements handy so we can talk through what you have today.
The Oklahoma Insurance Department has more information on severe storms, flood insurance, and earthquake insurance.