If I Hit a Deer in Oklahoma, Will My Car Insurance Cover It?

Mark Merritt
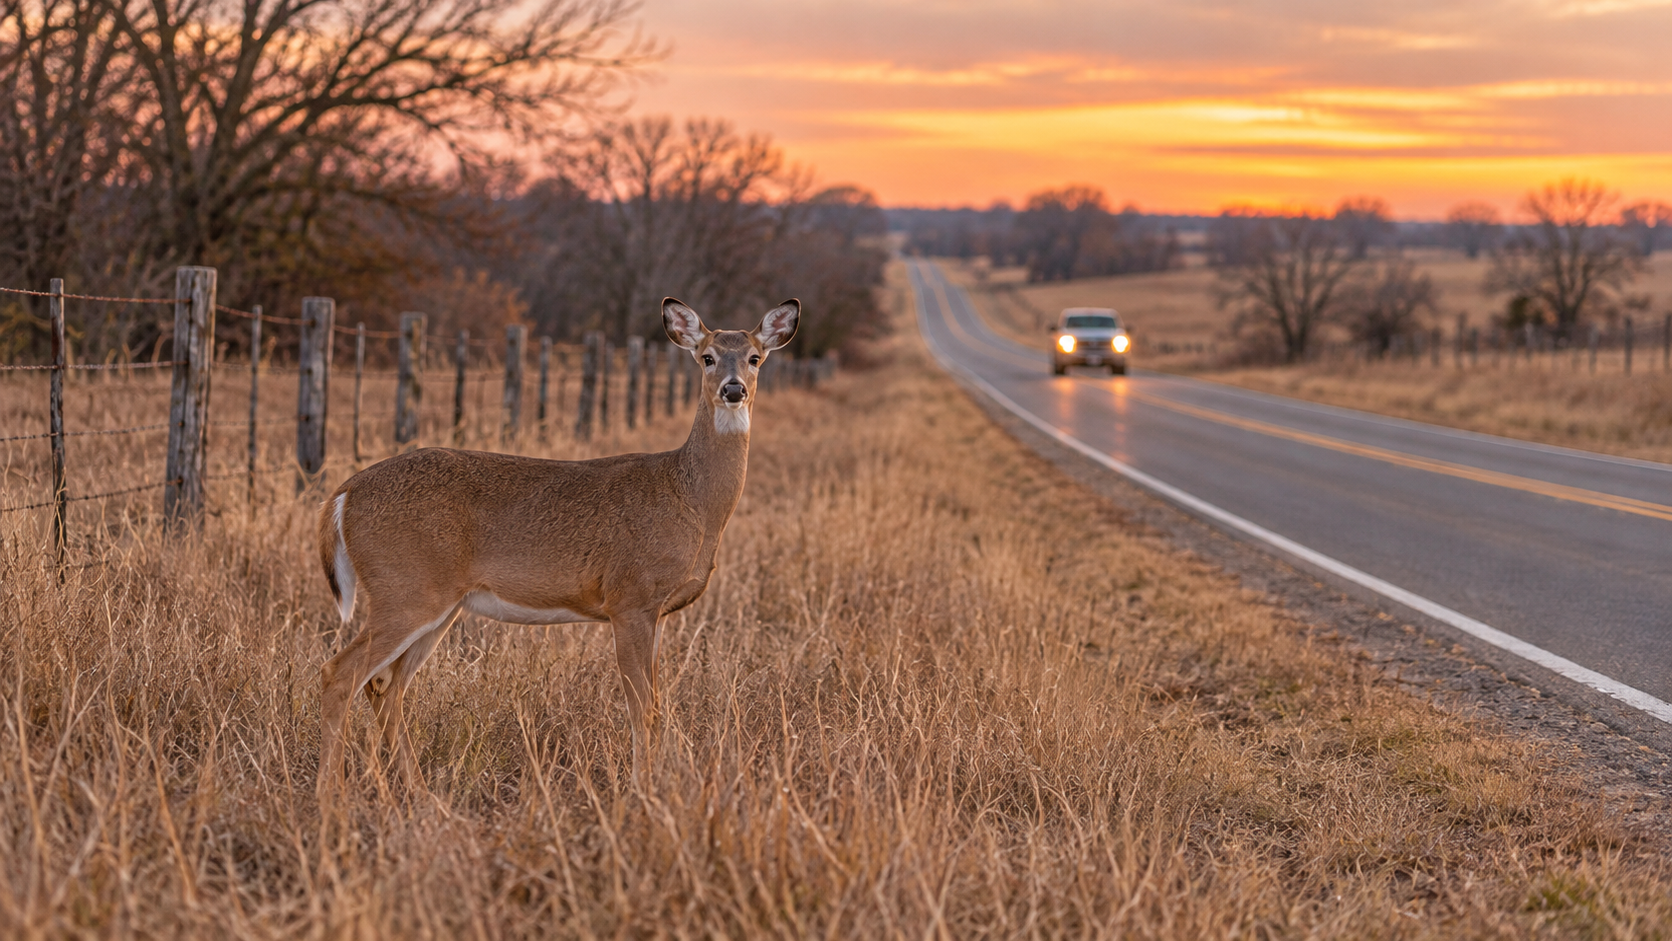
Say you’re headed home from Thanksgiving dinner with a plate of leftovers riding shotgun. A deer steps out of the ditch. By the time you get stopped, you’ve got a busted headlight and sweet potatoes in the floorboard. Everybody’s okay. You walk around to the front of the truck, take one look at that bent hood and wonder, “Am I paying for this, or is my insurance?”
If your truck made contact with the deer, the first thing I’d look for on your Oklahoma auto policy is comprehensive coverage. If you have it on that truck, it generally helps pay for the damage after your deductible. If you missed the deer and hit something else, we’d be looking at a different line on the same page.
What if I hit the deer?
It sounds reasonable to call it a collision. After all, you and that deer certainly collided. But on an auto policy, hitting an animal generally falls under comprehensive, sometimes listed as “other than collision.” That’s the same coverage you’d look at if hail put dents all over your hood while the truck was parked in your driveway. The Oklahoma Insurance Department explains how deer damage is covered.
Say the body shop and your insurance company agree it’ll take $3,200 to repair the covered damage. Your comprehensive deductible is $500. That leaves $2,700 for the insurance company and $500 for you. If you carry liability only on that truck, you’d be looking at the whole repair bill yourself. Liability covers injuries or damage you cause to somebody else, so it won’t buy you a new headlight for your own truck.
What if I miss the deer and hit a fence?
Run that same drive home one more time. This time the deer makes it across untouched, but your front bumper catches a fence post. Same stretch of Oklahoma road, same phone call to your agent, and probably the same mess on the floorboard. One detail changes the conversation: what did the truck actually hit?
Damage to your truck from hitting the fence generally falls under collision coverage, if you carry it. Your collision deductible can be different from your comprehensive deductible. With a $1,000 collision deductible and that same $3,200 covered repair, your share would be $1,000. The fence owner’s repair is a separate question. If you’re responsible for the damage, that’s where your property damage liability coverage may come in.
How do I check my coverage before the drive home?
Pull up your declarations page. That’s the policy summary with your vehicles and coverages. Find the truck you’re actually driving and look for the lines marked “Comprehensive” and “Collision.” Check the deductible beside each one. If you’ve also got a newer car on the policy, it’s worth checking both vehicles. It’s easy to remember picking a $500 deductible and forget which vehicle you picked it for.
If either line is missing or you can’t tell what the numbers mean, here’s what I’d ask your agent: “If I hit a deer in this truck tonight, what would I owe the body shop? And what would I owe if I missed it and hit a fence?” You ought to be able to leave that conversation with two plain answers.
If you want us to go through your Oklahoma auto policy with you, reach out to County Line Coverage. We’ll look at the truck you drive, what you carry on it and what a different deductible would actually cost. If I’d keep what you’ve got, I’ll tell you that, too. We’d love to help out.